Key Takeaways
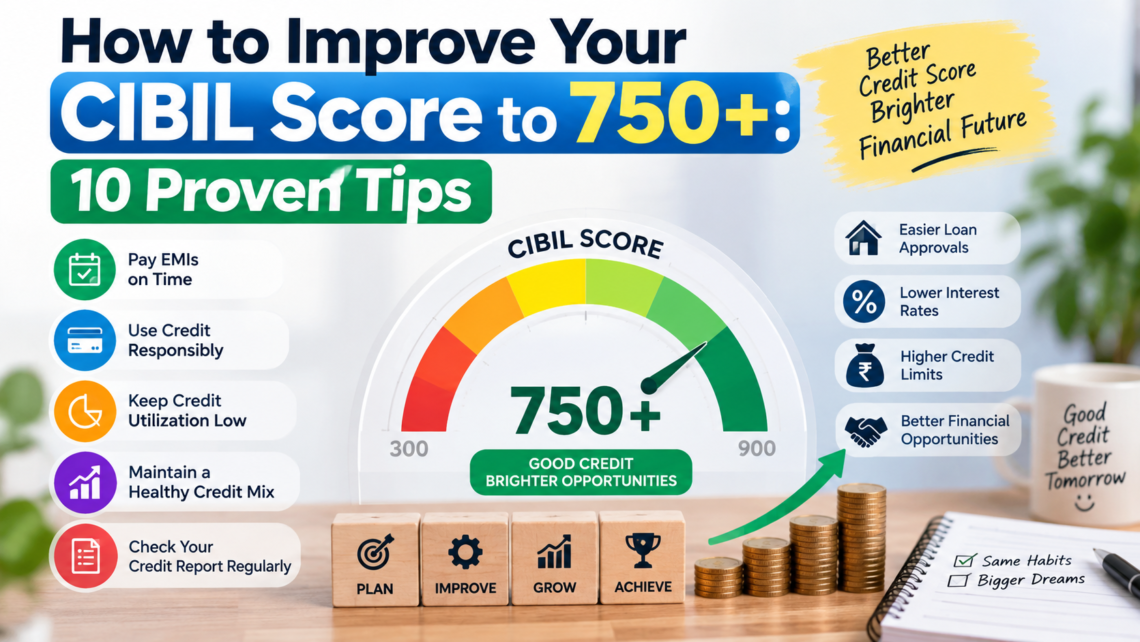
In short: To reach a 750+ CIBIL score, four things matter most — paying on time, keeping your credit utilization low, maintaining a healthy credit mix, and checking your report regularly. This guide breaks down every point in detail with tables and bullets so you can improve your score step by step.
- 750–900 score = Excellent, fastest loan approvals and the best interest rates
- Since 1 July 2026, RBI’s weekly credit-reporting rule means good repayment behaviour now shows up in your score faster
- 10 proven tips covering repayment, utilization, credit mix, and report monitoring
- With disciplined habits, moving from 650 to 750 in 6–12 months is realistic
- Common mistakes that quietly pull your score down are also covered
- A click-to-expand FAQ section is at the very end
What Is a CIBIL Score and Why Does 750+ Matter
Summary: A CIBIL score is a number between 300 and 900 built from your repayment history. A score of 750+ gets you the fastest approvals and the lowest interest rates, while a low score can mean rejection or a costlier loan.
TransUnion CIBIL calculates this score from your past loan and credit card repayment behaviour. It’s the first thing banks, NBFCs, and credit card companies check before looking at anything else on your application. First-time credit users with no loan or card history are shown “NA” or “NH” (No History) — that simply means there’s no record yet, not a poor score.
Even a small change can have a big financial impact. For example, moving a home loan score from 650 to 750+ can lower the interest rate enough to save lakhs of rupees over the loan’s tenure. That’s why your score is worth treating as a core indicator of your financial health, not just a number.
| Score Range | Category | Effect on Loans |
|---|---|---|
| 750–900 | Excellent | Fastest approval, best interest rates, higher credit limits |
| 700–749 | Good | Approval likely, but the sharpest rates may stay out of reach |
| 650–699 | Fair | Conditional approval — co-applicant or extra documents may be required |
| 300–649 | Poor | Most unsecured loans get rejected |
Key points:
- The higher the score, the lower the interest rate
- Repayment history is the single biggest factor (around 35%)
- NA/NH means no credit history — not a poor score
- Your score updates continuously; it’s a dynamic number, not fixed
The New 2026 RBI Rule: Weekly Credit Reporting
Summary: Since 1 July 2026, lenders must report repayment data to credit bureaus every week, so good behaviour reflects in your score far faster than before.
Previously, credit bureaus received data every fortnight (15 days), which meant a timely payment could take weeks to show up in your score. Under the new rule, that gap has shrunk considerably, giving disciplined borrowers a faster payoff for good behaviour and better control when planning a loan application.
- Before: fortnightly (15-day) reporting cycle
- Now (from 2026): weekly reporting cycle
- Benefit: on-time payments can start reflecting within days
- Planning your score ahead of a loan application is now easier
10 Proven Tips to Reach a 750+ CIBIL Score
Summary: The table below gives you the 10 most important actions and their effect on your score at a glance; each tip is then explained in detail so you can apply it practically.
| Tip | Effect on Score |
|---|---|
| Pay EMIs/bills on time | The single biggest positive factor (~35%) |
| Keep utilization under 30% | High utilization drags the score down fast |
| Dispute report errors | Removes incorrect negative entries |
| Avoid multiple applications | Every hard inquiry causes a temporary dip |
| Keep old accounts open | A longer history strengthens your score |
| Maintain a healthy credit mix | A secured + unsecured balance looks stronger |
| Clear settled accounts | A “settled” status can stay negative |
| Request a credit limit increase | Automatically lowers your utilization ratio |
| Monitor guarantor loans | Someone else’s default can hit your score too |
| Check your report regularly | Catches errors before they cause damage |
In detail:
- Pay every EMI and credit card bill on time — set up auto-debit or reminders so you never miss a due date; even one missed payment can hurt your score for months.
- Keep credit utilization under 30% — if your limit is ₹1 lakh, avoid spending more than ₹30,000 a month; for a score of 800+, aim closer to 10%.
- Check your free CIBIL report once a year and dispute any incorrect entries (wrong account, wrongly marked late payment) right away.
- Avoid applying for multiple loans or cards at once — every hard inquiry affects your score and makes you look “credit-hungry” to lenders.
- Don’t close old, well-managed credit card accounts — a longer credit history always works in your favour.
- Maintain a healthy mix of secured (car, home) and unsecured (personal loan, credit card) credit.
- Fully pay off settled or written-off accounts so they’re marked “closed” rather than “settled.”
- If your utilization stays consistently high, ask your bank for a credit limit increase — this lowers your ratio without cutting your spending.
- Keep an eye on guarantor or co-signed loans — if the other party defaults, your score takes the hit too.
- Monitor your CIBIL report once a month — it lets you track progress and catch errors early.
Common Mistakes That Pull Your Score Down
Summary: A few common mistakes people make without realising it can undo all the progress from the tips above — avoiding them matters just as much as following the tips themselves.
- Paying only the minimum due and carrying forward a balance (increases interest and keeps utilization high)
- Applying for several loans or cards in the same month
- Stopping card usage entirely (inactivity can weaken your profile too)
- Ignoring report errors instead of disputing them
- Becoming a guarantor without checking the other party’s repayment capacity
Practical Benefits of a 750+ Score
Summary: A 750+ score isn’t just about approval — it brings multiple benefits across your financial life, summarised in the table below.
| Benefit | How You Get It |
|---|---|
| Lower interest rates | Lenders treat you as low-risk |
| Higher loan/card limits | Reflects stronger creditworthiness |
| Faster approvals | Less documentation and verification |
| Better negotiating power | Multiple lenders compete for you |
| Pre-approved offers | Banks reach out to you proactively |
How Long Does It Take to Improve Your Score
Summary: No article can guarantee exact points, since it depends on your entire credit file, but consistent good behaviour follows a realistic timeline, shown below.
| Time Period | What to Expect |
|---|---|
| 1–3 months | Small improvements from better utilization and payment timing |
| 3–6 months | Meaningful gains from consistent clean history |
| 6–12 months | Realistic window to go from 650 to 750+ |
| 12–24 months | Needed to repair the score after serious defaults or write-offs |
FAQs
Summary: Quick, direct answers to common questions below — tap or click any question to expand its answer.
How long does it take to reach a 750+ CIBIL score?
It depends on your current score and history. Starting from 650–700 with disciplined habits, reaching 750+ in 6 to 12 months is realistic.
What credit utilization ratio should I maintain?
Keep it under 30% of your total credit limit; for an excellent score, aim closer to 10%.
Should I check my CIBIL score before applying for a loan?
Yes — it tells you your approval chances in advance and helps you avoid unnecessary hard inquiries.
How often can I check my CIBIL report for free?
You can get a full free report from the official CIBIL website once every calendar year.
What should I do if I find an error in my CIBIL report?
Raise a dispute through CIBIL’s resolution process; once the incorrect entry is corrected, your score can improve.