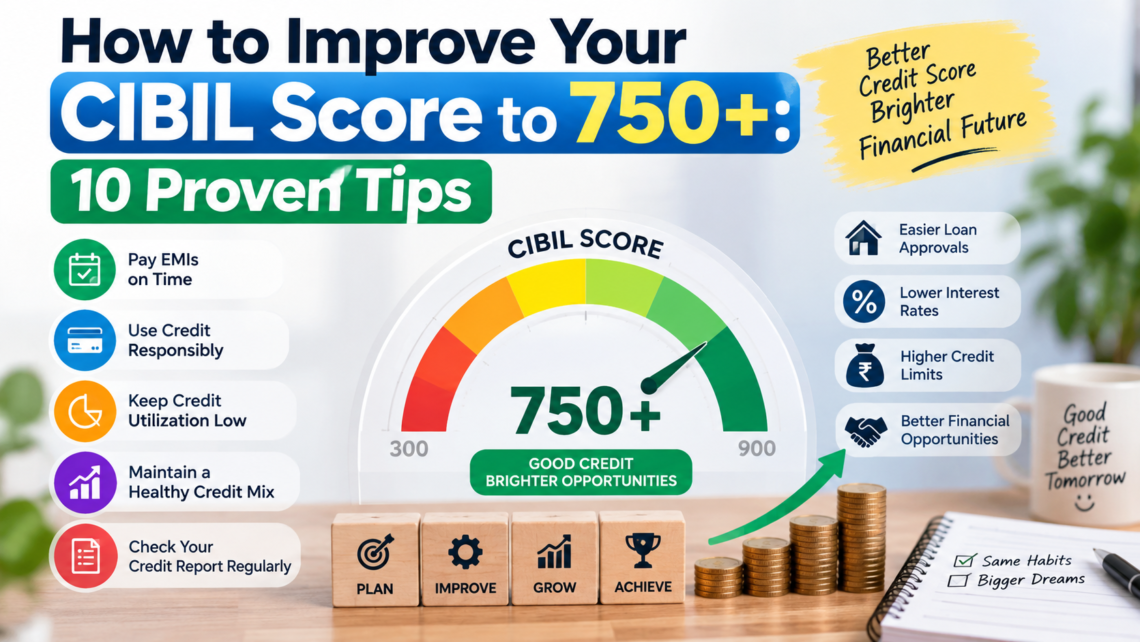
To improve your CIBIL score to 750+, pay every EMI and credit card bill on time, keep credit utilization below 30%, avoid multiple loan applications, maintain a healthy credit mix, and fix errors in your credit report. Small gains show in 1-3 months; larger recovery takes 6-12 months.
Summary
Improving your CIBIL score to 750+ comes down to consistent, disciplined credit habits. Pay every EMI and credit card bill on time, since payment history has the biggest impact on your score. Keep your credit utilization below 30%, avoid applying for multiple loans or cards in a short period, and maintain a healthy mix of secured and unsecured credit. Check your credit report regularly and fix errors quickly. Small gains can appear within 1-3 months, while recovering from a score below 650 usually takes 6-12 months.
Key Takeaways
- Payment history is the number one factor in your CIBIL score.
- Keep credit utilization below 30% (ideally 10-15%).
- Avoid too many hard enquiries; leave 3-6 months between applications.
- Check your credit report at least once a year and dispute errors.
- Avoid “Settled” status; aim for “Closed” with full repayment.
- There are no shortcuts. Consistency over 6-12 months works.
Table of Contents
What Is a CIBIL Score?
A CIBIL score is a 3-digit number between 300 and 900 that represents your creditworthiness. It is generated by TransUnion CIBIL, India’s first credit information company, using the data in your credit report: loans, credit cards, repayment behavior and enquiries. The closer your score is to 900, the more reliable you appear to lenders.
Banks and NBFCs use this score to decide whether to approve your loan or credit card, and at what interest rate. Even if your income is strong, a weak CIBIL score can lead to rejection or costlier borrowing, which is why understanding it is the first step to improving it.
A CIBIL score is different from a CIBIL report. The score is a 3-digit summary, while the report is the detailed record of all your credit accounts and enquiries.
CIBIL Score Range: What Does Your Score Mean?
Lenders usually group scores into bands. Knowing where you stand helps you set a realistic target and understand how lenders are likely to view your application.
| CIBIL Score Range | Rating | What It Means for You |
|---|---|---|
| 300-549 | Poor | Very low chances of approval; high interest rates if approved |
| 550-649 | Fair | Limited options; approval possible with conditions |
| 650-749 | Good | Decent approval chances; interest rates may not be the lowest |
| 750-900 | Excellent | High approval chances, better interest rates, faster processing |
Note: Score bands may vary slightly across lenders.
Why Is a CIBIL Score of 750+ Important?
A score of 750 or above is widely treated as the benchmark for “good credit” in India. At this level, lenders see you as a low-risk borrower, which gives you more choice and better terms across almost every type of credit product. Over the life of a large loan such as a home loan, even a small reduction in interest rate can save you lakhs of rupees.
- Easier approvals: Lenders see you as a low-risk borrower.
- Lower interest rates: You may qualify for better rates on home, car and personal loans.
- Higher credit limits: Banks may offer bigger limits on credit cards.
- Negotiation power: You can ask for reduced processing fees or better terms.
- Faster processing: Pre-approved offers and quicker disbursals are more likely.
Before applying for a big loan like a home loan, check your CIBIL score 3-6 months in advance so you have time to fix problems.
What Affects Your CIBIL Score?
Your CIBIL score is not random. It is calculated from a few clear factors in your credit report, and some carry much more weight than others. Understanding these factors tells you exactly where to focus your effort first, so you don’t waste time on habits that barely move the needle.
| Factor | Approx. Importance* | What Lenders Look At |
|---|---|---|
| Payment history | Highest (~30%) | On-time vs. late or missed payments |
| Credit utilization / exposure | High (~25%) | How much of your credit limit you use |
| Credit mix and duration | High (~25%) | Secured vs. unsecured loans; age of accounts |
| Other factors (new enquiries, etc.) | Moderate (~20%) | Number of recent credit applications |
*Weightages are commonly cited estimates and not official figures published by CIBIL.
10 Proven Tips to Improve Your CIBIL Score to 750+
The tips below are practical, realistic and based on how credit scoring works in India. You don’t need to apply all ten at once. Start with the first three, which have the biggest impact, and add the others gradually.
1. Pay All EMIs and Credit Card Bills on Time
Payment history is the single most important factor in your CIBIL score. Even one late payment can pull your score down, and late payments can stay visible on your report for years. Lenders read a consistent on-time record as proof that you will repay future loans responsibly, so this habit alone can drive most of your improvement.
What to do
- Set up auto-debit for all EMIs and minimum card dues.
- Set calendar reminders 3-5 days before the due date.
- Pay the full statement balance on credit cards whenever possible, not just the minimum due.
2. Keep Your Credit Utilization Below 30%
Credit utilization ratio shows lenders how dependent you are on borrowed money. If your card limit is ₹1,00,000 and you spend ₹60,000, your utilization is 60%, which is too high and can hurt your score even if you repay on time. Keeping this ratio low is one of the fastest ways to see a score improvement.
Credit Utilization Ratio = (Credit Used ÷ Total Credit Limit) × 100
Example: ₹25,000 used on a ₹1,00,000 limit = 25% (within the safe zone).
25% used, below the 30% limit
What to do
- Aim to use less than 30% of your limit (under 10-15% is even better).
- Make multiple small payments in a month instead of one large payment at the end.
- Ask your bank for a credit limit increase (only if you won’t spend more).
3. Don’t Apply for Too Many Loans or Cards at Once
Every time you apply for credit, the lender makes a hard enquiry on your report. A few enquiries spread over time are normal, but many in a short period make you look credit-hungry, which lenders see as a sign of financial stress. Each hard enquiry can lower your score slightly, and the effect adds up quickly.
What to do
- Apply only when you truly need credit.
- Use eligibility checkers or soft enquiry tools before applying.
- Leave a gap of at least 3-6 months between applications.
4. Maintain a Healthy Credit Mix
Lenders like to see that you can manage different types of credit responsibly. A balanced mix of secured and unsecured loans shows financial maturity and lowers the perceived risk of lending to you. However, a healthy mix builds up naturally over time, so it should never push you into borrowing you don’t need.
| Type | Examples |
|---|---|
| Secured loans | Home loan, car loan, gold loan |
| Unsecured loans | Personal loan, credit card |
What to do
- Don’t rely only on credit cards or only on personal loans.
- Add a different type of credit only if you genuinely need it. Never borrow just to improve your score.
5. Check Your Credit Report Regularly and Fix Errors
Credit reports sometimes contain mistakes, and these errors can quietly damage your score. Wrong late-payment entries, closed loans showing as active, duplicate accounts or accounts you never opened are common examples. Since you may not even know about them, regular checks are essential, and correcting an error can lift your score without any change in your behavior.
What to do
- Download your credit report at least once a year (free from the bureau’s official website as per RBI norms). Checking every 3-4 months is even better.
- Raise a dispute on the CIBIL website with supporting documents if you spot an error.
- Follow up with the lender so that the correction is reflected in your report.
Keep screenshots and payment receipts of closed loans. They are your strongest proof when disputing an error.
6. Don’t Close Your Oldest Credit Card
Credit history length matters because it shows how long you have been managing credit. An old account with good payment behavior is a strong signal of long-term reliability. Closing it can shorten your average credit age and reduce your total available limit, which may push your utilization higher.
What to do
- Keep your oldest card active with small, regular purchases that you repay in full.
- Close a card only if it has a high annual fee and you have no other option, and check the impact on your total credit limit first.
7. Clear Outstanding Dues and Avoid “Settled” Status
If you settle a loan or card for less than the full amount, it is marked as “Settled” on your report, which lenders view negatively. The preferred status is “Closed” after full repayment. A “Settled” tag can remain visible for years and can make future loan approvals harder, even if your score later recovers.
What to do
- Repay dues in full wherever possible.
- If you’re in financial trouble, talk to your lender about restructuring or EMI relief before defaulting.
- If an account is already settled, work toward full payment and request an updated status.
8. Be Careful With Co-Signing and Guaranteeing Loans
When you become a co-applicant or guarantor, you share legal responsibility for the loan. The loan appears on your credit report too, so if the main borrower misses payments, your score suffers along with theirs. Many people damage their credit this way without ever borrowing a rupee themselves.
What to do
- Co-sign only for people you fully trust.
- Monitor the loan’s repayment status regularly.
9. Don’t Max Out Cards or Use Them for Cash Withdrawals
Withdrawing cash on a credit card attracts high fees and interest that starts immediately, with no interest-free period. It can also signal financial stress to lenders, and maxing out your card pushes your utilization ratio dangerously high. Both habits can weaken your credit profile quickly.
What to do
- Avoid cash advances unless there is a real emergency.
- Use a debit card, UPI or a personal loan for cash needs when feasible.
10. Be Patient and Stay Consistent
There is no legitimate overnight trick to jump to 750. Credit scores improve through consistent, good behavior over time. Be careful of anyone promising to “repair your CIBIL score instantly” for a fee, as such claims are usually misleading or fraudulent. Slow, steady improvement is what lenders trust the most.
What to do
- Track your score monthly.
- Stick to the habits above for at least 6-12 months.
How Long Does It Take to Improve Your CIBIL Score?
The time needed depends on your starting point and how consistently you follow good credit habits. A recent late payment can be recovered from quickly, while serious defaults or settled accounts take much longer. The table below gives a realistic idea of what to expect.
| Starting Situation | Typical Time to See Improvement* |
|---|---|
| Minor dip (from a recent late payment or high utilization) | 1-3 months |
| Score between 650-699 | 3-6 months |
| Score below 650 (multiple defaults or high utilization) | 6-12+ months |
| Settled/written-off accounts | 12+ months, with consistent on-time payments |
*Timelines are indicative and vary by individual credit profile.
Common Mistakes That Keep Your CIBIL Score Low
Sometimes the problem is not what you are missing but what you are doing wrong. Many borrowers repeat the same avoidable mistakes, which keep their score stuck below 750 for years. Fixing even a couple of these can make a visible difference.
- Paying only the minimum due every month
- Missing even a single EMI
- Applying for multiple loans in a short period
- Ignoring errors in the credit report
- Closing old credit cards without a plan
- Using more than 50% of the credit limit regularly
Quick 30-Day Action Plan
If you’re not sure where to begin, this simple four-week plan breaks the process into manageable steps. It won’t take you to 750 in a month, but it sets up the habits and fixes that make steady improvement possible.
| Week | Action |
|---|---|
| Week 1 | Download your CIBIL report and check for errors or wrong entries |
| Week 2 | Set up auto-pay for all EMIs and card bills; raise disputes if needed |
| Week 3 | Reduce card balances to bring utilization below 30% |
| Week 4 | Pause new credit applications and review your budget for timely repayments |
Conclusion
Improving your CIBIL score to 750+ isn’t complicated, but it needs discipline and patience. Pay on time, keep your utilization low, apply for credit sparingly, and monitor your report regularly. Every good habit adds up over months and gradually builds the trust lenders look for. Start today with one small step, such as downloading your credit report, and your score will follow.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Score calculations and lender criteria may vary. Please check your official credit report and consult a qualified financial advisor for personalized guidance.
Frequently Asked Questions (FAQs)
1. What is a good CIBIL score in India?
A score of 750 or above is considered good to excellent by most lenders in India. At this level, you are more likely to get quick approvals and competitive interest rates.
2. Can I improve my CIBIL score from 600 to 750?
Yes, but it takes time. With on-time payments, low utilization and no new defaults, many people can see a significant improvement in 6-12 months or more, depending on their credit history.
3. How can I increase my CIBIL score quickly?
Pay all dues on time, reduce credit card utilization below 30%, and correct any errors in your report. These steps can show results within 1-3 months, though large jumps are not guaranteed.
4. Does checking my own CIBIL score reduce it?
No. Checking your own score is a soft enquiry and does not affect your score. Only hard enquiries made by lenders when you apply for credit can have an impact.
5. Does closing a credit card reduce the CIBIL score?
It can. Closing a card reduces your total available credit, which may raise your utilization, and it may shorten your credit history. Think carefully before closing an old card.
6. How often does the CIBIL score update?
Lenders report to credit bureaus periodically, and reporting has become more frequent under updated RBI norms. Your score updates whenever new data is received, so changes may appear within a few weeks.
7. Will paying off a loan early improve my score?
Closing a loan with full repayment is positive for your report, but a loan with a long, clean repayment record also helps your credit history. Choose based on your finances rather than only on your score.
8. Is a CIBIL score of 750 enough for a home loan?
In most cases yes, along with stable income and a good debt-to-income ratio. It can also help you negotiate a more competitive interest rate.
